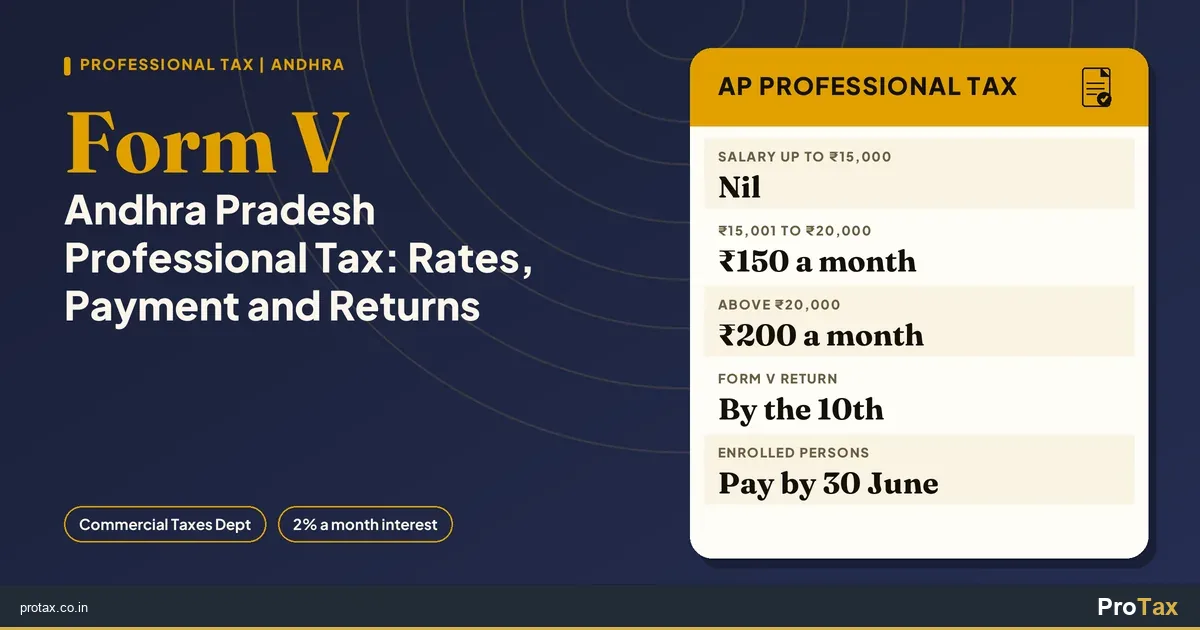
Andhra Pradesh professional tax is simple on the salary side and detailed on the business side. Employees pay nil up to ₹15,000 a month, ₹150 a month for ₹15,001 to ₹20,000 and ₹200 a month above that, a maximum of ₹2,400 a year with no February top-up. Businesses, professionals and directors pay a fixed annual amount, up to ₹2,500, from more than 40 entries in the First Schedule. Employers file Form V with the tax by the 10th of the following month, and enrolled persons pay before 30 June. The big 2025 change was administrative: from 1 April 2025, the Commercial Taxes Department took back collection from the municipal corporations, and all payments now run through its My Profession Tax portal. Here is the 2026 slab, who pays what, due dates, penalties and how to register.
- Salary slab: nil up to ₹15,000; ₹150 for ₹15,001 to ₹20,000; ₹200 above (per month).
- Collector: Commercial Taxes Department from 1 April 2025 (G.O. Ms. No. 63, 5 March 2025).
- Employers: Form V return with tax by the 10th of the next month.
- Enrolled persons: pay before 30 June, or within a month if enrolled after 31 May.
- Business rates: companies ₹2,500; directors ₹2,500; dealers nil, ₹1,250 or ₹2,500 by turnover.
- Interest: 2% a month on late tax; penalty 25% to 50% after a demand.
This article covers profession tax under the Andhra Pradesh Tax on Professions, Trades, Callings and Employments Act, 1987 and the Rules of 1987, as amended, including Act 42 of 2020. It does not cover Telangana, which runs its own adapted law, or other states. Rates in the First Schedule can be changed by notification under Section 37, so check the current schedule before paying.
What Is Professional Tax in Andhra Pradesh?
Professional tax in Andhra Pradesh is a State tax on professions, trades, callings and employments levied under Section 4 of the Andhra Pradesh Tax on Professions, Trades, Callings and Employments Act, 1987, for the benefit of the State. Every person engaged in a profession, trade, calling or employment in Andhra Pradesh who falls in a class in column (2) of the First Schedule pays the rate in column (3). Salaried employees pay through their employer, who deducts the tax before paying salary under Section 5 and holds a certificate of registration under Section 6(1). Everyone else liable, such as companies, directors, dealers, contractors and professionals, holds a certificate of enrolment under Section 6(2) and pays once a year. The Act replaced the profession taxes that local bodies used to levy, and Section 32 bars any local authority from levying one. Under Article 276 of the Constitution, no person pays more than ₹2,500 a year.
The Act calls taxpayers "assessees". Employers file monthly returns; enrolled persons do not file returns, but pay the amount stated in their enrolment certificate.
Levy: Section 4 and the First Schedule of the Andhra Pradesh Tax on Professions, Trades, Callings and Employments Act, 1987 (Act 22 of 1987), last substantially amended by Act 42 of 2020. Employer deduction: Section 5. Registration and enrolment: Section 6. Returns: Section 7 and Rule 12 (Form V). Enrolled persons' payment: Section 10. Interest and penalties: Sections 11 and 12. Collection: G.O. Ms. No. 63 dated 5 March 2025. Registration, returns and payment: Commercial Taxes Department, Andhra Pradesh; bare Act on India Code.
AP Professional Tax Slab for Salaried Employees
| Monthly Salary or Wage | Tax per Month | Tax per Year |
|---|---|---|
| Up to ₹15,000 | Nil | Nil |
| ₹15,001 to ₹20,000 | ₹150 | ₹1,800 |
| Above ₹20,000 | ₹200 | ₹2,400 |
The slab has applied since the First Schedule was substituted in 2013, and it is the same for men and women. Salary for this purpose, under Section 2(m), includes pay, dearness allowance, other regular remuneration and perquisites taxable under the Income-tax Act, but excludes bonus and gratuity. So a festival bonus does not move an employee from ₹150 to ₹200 that month.
A person who is salaried but also falls under a higher entry, such as a doctor in practice for more than five years, or who works for two employers at once, can give the employer a certificate and enrol to pay the tax personally under the proviso to Section 5. The employer then stops deducting it.
Rates for Businesses, Professionals and Directors
| Entry | Class | Annual Tax |
|---|---|---|
| 2 | Legal practitioners, medical practitioners, engineers, architects, consultants and similar professionals | Nil up to 5 years' standing; ₹2,500 after 5 years |
| 4 | Contractors | Nil below ₹10 lakh; ₹2,000 for ₹10 lakh to ₹25 lakh; ₹2,500 above ₹25 lakh |
| 5 | Directors of companies (other than Government nominees) | ₹2,500 |
| 8 | GST or VAT registered dealers, and shopkeepers employing staff | Nil below ₹10 lakh; ₹1,250 for ₹10 lakh to ₹50 lakh; ₹2,500 above ₹50 lakh |
| 9 | Owners or lessees of factories | Nil below ₹10 lakh; ₹2,000 for ₹10 lakh to ₹25 lakh; ₹2,500 above ₹25 lakh |
| 14 | Hotels, restaurants, bars and lodging houses | Nil below ₹10 lakh; ₹2,000 for ₹10 lakh to ₹25 lakh; ₹2,500 above ₹25 lakh |
| 20 | Companies (not dealers) with turnover of ₹10 lakh or more | ₹2,500 |
| 21 | Each partner of a firm drawing remuneration | ₹2,500 |
| 39A | Restaurants, takeaway food points, canteens and curry points | ₹2,500 |
The Schedule runs to more than 40 entries, covering banks and each branch, telecom and internet providers, call centres, educational institutions, property developers, transport companies, money lenders and others, most at ₹2,500 a year. A residuary entry covers any other person engaged in a profession, trade or calling with annual income above ₹1,80,000. Where a person falls under more than one entry, the highest rate applies.
Who Collects AP Professional Tax: The 2025 Change
| Period | Collecting Authority |
|---|---|
| April 1987 to July 2012 | Commercial Taxes Department |
| August 2012 to 31 March 2025 | Municipal corporations and other local bodies, as collecting agents |
| From 1 April 2025 | Commercial Taxes Department, under G.O. Ms. No. 63 dated 5 March 2025 |
Section 14 of the Act lets the Government appoint a department officer or local authority as a collecting agent, which is how the municipal corporations collected the tax for over a decade. The 2025 order brought it back to the Commercial Taxes Department. Since 1 April 2025, taxpayers pay only to the department, through the My Profession Tax portal on apct.gov.in. Payments made to a municipal corporation after that date are not the right channel, so an employer that used to pay a corporation should move its registration and payments to the portal.
Need Help With AP Professional Tax?
ProTax provides assistance for profession tax registration and enrolment with the Commercial Taxes Department, Andhra Pradesh, including Form V filing set-up and migration from earlier municipal payments. Professional charges start at ₹999. Profession tax, interest and penalties are paid separately at actuals.
Due Dates for AP Professional Tax
| Who | What | When |
|---|---|---|
| New employer or enrolled person | Apply for registration or enrolment | Within 30 days of becoming liable (Section 6(3)) |
| Registered employer | Form V return with tax | By the 10th of the month after the month concerned (Rule 12(1)) |
| Enrolled before the year or by 31 May | Annual tax | Before 30 June (Section 10(a)) |
| Enrolled after 31 May | Annual tax | Within one month of enrolment (Section 10(b)) |
| Assessee served with a demand | Assessed tax | Within 15 days of the notice of demand (Section 8(4)) |
A return under Section 7(2) must be accompanied by proof of payment of the full tax due, and a return without it is not treated as submitted. For employers, that makes the 10th a payment date as well as a filing date.
A Monthly Cycle in Practice
Take an employer that pays October salaries on 31 October. It deducts ₹150 or ₹200 from each employee above ₹15,000, according to the slab, and by 10 November files the Form V return for October with the tax paid on the portal. Salaries for November, paid on 30 November, go into the return due by 10 December, and so on through the year. Enrolled persons run a separate, annual cycle: the company, each director and any partners pay their certificate amounts before 30 June, independent of the monthly returns.
How to Register and Pay on the My Profession Tax Portal
- Open the portal: on apct.gov.in, go to My Profession Tax and choose the taxpayer login.
- Choose the certificate: registration (Form I) if you are an employer deducting tax from staff; enrolment (Form II) if you pay on your own account. Many businesses need both.
- Enter details: PAN, constitution (company, firm, proprietor), address of each place of business, GST registration if any, turnover or standing in profession, and employee details for registration.
- Upload documents: incorporation certificate or partnership deed, address proof or lease of premises, and authorisation for the signatory.
- Get the certificate: the department's ease-of-doing-business instructions call for online registrations to be approved within one day.
- File and pay: employers file Form V with payment by the 10th; enrolled persons pay the certificate amount before 30 June.
Under the Act's definition of "person", every branch of a firm, company or other body is treated as a separate person, so a business with branches in Visakhapatnam and Vijayawada should check whether each branch needs its own enrolment.
Interest and Penalties
| Default | Consequence | Provision |
|---|---|---|
| Late registration (employer) | ₹10 to ₹20 per day | Section 6(5) |
| Late enrolment (others) | Up to ₹5 per day | Section 6(5) |
| False information in application | ₹100 to ₹1,000 | Section 6(6) |
| Late Form V return | ₹5 to ₹100 per day | Section 7(3) |
| Failure to deduct or pay | Assessee in default; simple interest at 2% a month or part | Section 11, Form V |
| Non-payment after demand | Penalty of 25% to 50% of tax, plus interest | Section 12 |
| Wilful non-disclosure found in assessment | Penalty of 1.5 to 3 times the tax | Section 8(5) |
| Non-compliance with the Act (on conviction) | Fine of ₹500 to ₹5,000; ₹10 to ₹50 a day if continuing | Section 22 |
Arrears are recoverable as arrears of land revenue under Section 13, and Section 18 lets officers recover dues directly from the assessee's bank or debtors. Assessments can reach back four years from the end of the year concerned under Sections 8(2) and 9. Section 25 allows offences to be compounded.
Section 5(1) makes the employer liable to pay the tax on behalf of every employee when salary is paid, whether or not it was actually deducted. An employer that forgot to deduct ₹200 a month from a ₹25,000 employee owes ₹2,400 a year for that employee, plus interest at 2% a month. In a company, Section 23 also extends offences to the persons in charge of the business.
Worked Examples
| Taxpayer | Certificates | Annual Tax |
|---|---|---|
| Visakhapatnam IT company, ₹3 crore turnover, GST-registered, 2 directors, 30 staff on ₹40,000 | Company enrolment, 2 director enrolments, registration | Company ₹2,500; directors ₹5,000; staff 30 × ₹2,400 = ₹72,000 via Form V |
| Vijayawada retail shop, ₹30 lakh turnover, 3 staff on ₹14,000 | Enrolment (entry 8); registration not needed as staff are below ₹15,000 | ₹1,250 |
| Guntur doctor, 8 years in practice | Enrolment (entry 2) | ₹2,500 |
| Junior advocate, 3 years in practice | None, as tax is nil | Nil |
| Civil contractor, ₹18 lakh turnover | Enrolment (entry 4) | ₹2,000 |
| Tailoring unit run by the owner | None (entry 39 exemption) | Nil |
Based on our experience with Andhra Pradesh employers, the commonest question since the 2025 switch to the Commercial Taxes Department has been where to pay, from businesses that had paid the municipal corporation for years. Harith - Compliance Expert recommends confirming each registration and enrolment on My Profession Tax, checking every branch separately, filing Form V with payment before the 10th each month, and paying directors' and the company's enrolment tax before 30 June so the 2% monthly interest never starts.
Exemptions
- Low salary: monthly salary or wage up to ₹15,000 pays nil.
- Entry 39 classes: agriculturists; persons performing religious duties; skilled persons such as goldsmiths, blacksmiths, potters, basket makers, washermen, barbers, cobblers, tailors, carpenters, masons, plumbers, book binders, toddy tappers and electricians; persons with 40% or more disability; and dry cleaners.
- Small businesses: dealers, contractors, factories and hotels below ₹10 lakh turnover pay nil under their entries.
- New professionals: up to five years' standing pay nil under entry 2.
- Notified exemptions: Section 31 lets the Government exempt or reduce tax for any class by notification.
Income Tax Treatment
Salaried employees can deduct profession tax paid under Section 19 of the Income-tax Act, 2025 (Section 16(iii) of the 1961 Act up to FY 2025-26) only under the old tax regime; the new regime does not allow it (see professional tax under the new tax regime). Businesses claim profession tax paid as an expense under the usual rules.
Common Mistakes to Avoid
- Paying the municipal corporation after 1 April 2025, instead of the Commercial Taxes Department.
- Adding a ₹300 February deduction, which applies in Maharashtra, not Andhra Pradesh.
- Missing directors' enrolment, separate from the company's own ₹2,500.
- Counting bonus as salary for the slab, contrary to Section 2(m).
- Filing Form V without payment, which does not count as a return.
- Ignoring branches, each of which is a separate person under the Act.
Summary
Andhra Pradesh professional tax is nil on monthly salary up to ₹15,000, ₹150 for ₹15,001 to ₹20,000 and ₹200 above, up to ₹2,400 a year for employees. Companies, directors, partners and professionals pay fixed annual amounts up to ₹2,500 from the First Schedule, before 30 June. Employers file Form V with payment by the 10th of each following month. Since 1 April 2025, the Commercial Taxes Department collects the tax again, through My Profession Tax on apct.gov.in, with 2% monthly interest and a 25% to 50% penalty for defaults. For city help, see professional tax registration in Visakhapatnam and professional tax registration in Vijayawada; for payroll, our HR and payroll management services; and for how other states differ, see PTRC vs PTEC in Maharashtra and Kerala's half-yearly professional tax.
Professional Assistance for AP Professional Tax
ProTax provides assistance for profession tax registration, enrolment, Form V returns and annual payments with the Commercial Taxes Department, Andhra Pradesh. Professional charges start at ₹999. Profession tax, interest and penalties are paid separately at actuals.
Frequently Asked Questions
What is the professional tax slab in Andhra Pradesh for 2026?
For salary and wage earners, AP professional tax is nil up to ₹15,000 a month, ₹150 a month for ₹15,001 to ₹20,000, and ₹200 a month above ₹20,000, under entry 1 of the First Schedule to the Andhra Pradesh Tax on Professions, Trades, Callings and Employments Act, 1987. The same slab applies to men and women.
What is the maximum professional tax for an employee in Andhra Pradesh?
A salaried employee earning above ₹20,000 a month pays ₹200 a month, or ₹2,400 a year. Unlike Maharashtra, Andhra Pradesh has no higher February deduction. The ₹2,500 a year figure applies to enrolled persons such as companies, directors and professionals, which is the ceiling under Article 276 of the Constitution.
Who collects professional tax in Andhra Pradesh in 2026?
The Commercial Taxes Department collects profession tax from 1 April 2025, under G.O. Ms. No. 63 dated 5 March 2025. The department had collected it from 1987 to July 2012, after which municipal corporations handled it. Taxpayers now register, file and pay only on the department's portal.
How do I pay AP professional tax online?
Go to the Commercial Taxes Department website, apct.gov.in, open the My Profession Tax portal and use the taxpayer login. From there you can register, file the Form V return and pay online. Employers quote their registration number, and enrolled persons pay the annual amount shown in their enrolment certificate.
What is the due date for AP professional tax for employers?
Under Rule 12(1) of the AP profession tax Rules, as amended in 2011, an employer files the return in Form V along with the tax by the 10th day of the month after the month for which the return is due. So tax deducted from salaries paid in October is due by 10 November.
When must enrolled persons pay AP professional tax?
Under Section 10 of the Act, an enrolled person pays the year's tax before 30 June if enrolled before the year began or on or before 31 May. A person enrolled after 31 May pays within one month of the date of enrolment. The amount is stated in the enrolment certificate.
What is the difference between registration and enrolment in AP professional tax?
A registration certificate under Section 6(1) is held by an employer that deducts tax from employees' salaries and files Form V returns. An enrolment certificate under Section 6(2) is held by a company, director, professional, dealer or other person liable to pay the tax on their own account, usually once a year.
How much professional tax does a company pay in Andhra Pradesh?
A company registered under the Companies Act with turnover of ₹10 lakh or more pays ₹2,500 a year under entry 20. A company that is a GST-registered dealer falls under entry 8, with ₹1,250 for turnover of ₹10 lakh to ₹50 lakh and ₹2,500 above ₹50 lakh. The highest applicable entry governs.
Do directors pay professional tax in Andhra Pradesh?
Directors of companies, other than those nominated by the Government, are covered by entry 5 of the First Schedule at ₹2,500 a year. They take an enrolment certificate and pay the tax themselves. Where a director also draws salary, the annual cap of ₹2,500 per person still applies.
Do doctors and lawyers pay professional tax in Andhra Pradesh?
Professionals under entry 2, including legal practitioners, medical practitioners, engineers, architects and consultants, pay nil if their standing in the profession is up to five years, and ₹2,500 a year if it is more than five years. They enrol and pay by 30 June each year.
How much professional tax do shops and dealers pay in AP?
Under entry 8, GST-registered dealers and shopkeepers who employ staff under the AP Shops and Establishments Act pay nil below ₹10 lakh annual turnover, ₹1,250 a year for ₹10 lakh to ₹50 lakh, and ₹2,500 a year above ₹50 lakh. Restaurants, takeaways and curry points are under entry 39A at ₹2,500.
What is the penalty for late AP professional tax registration?
Under Section 6(5) of the Act, the assessing authority can impose a penalty of ₹10 to ₹20 per day of delay on an employer and up to ₹5 per day on others, after a hearing. Apply within 30 days of becoming liable. Deliberately false information in the application attracts a penalty of ₹100 to ₹1,000.
What is the interest on late payment of AP professional tax?
Section 11 makes an employer who fails to deduct or pay the tax an assessee in default, liable to interest for each month or part of the delay. Form V computes simple interest at 2% a month or part. The same applies to enrolled persons who pay late under Section 11(2).
What is the penalty for not paying AP professional tax after a demand?
If an assessee fails, without reasonable cause, to pay within the time in the notice of demand, Section 12 allows a penalty of 25% to 50% of the tax due, in addition to interest. Arrears of tax, penalty and interest are recoverable as arrears of land revenue under Section 13.
Is there a penalty for late Form V returns?
Under Section 7(3), if a registered employer fails without reasonable cause to submit the return within the specified period, the assessing authority can impose a penalty of ₹5 to ₹100 for each day of delay, after giving an opportunity to make a representation. A return without proof of tax payment is not treated as filed.
Who is exempt from professional tax in Andhra Pradesh?
Entry 39 of the First Schedule exempts agriculturists, persons performing religious duties, listed skilled workers such as goldsmiths, tailors, carpenters, plumbers and electricians, persons with 40% or more disability and dry cleaners. Salaried persons up to ₹15,000 a month pay nil. Section 31 lets the State notify further exemptions.
Is bonus included in salary for AP professional tax?
Section 2(m) of the Act defines salary or wages to include pay, dearness allowance, all other regular remuneration and perquisites under Section 17 of the Income-tax Act, 1961, but not bonus or gratuity. So the slab is applied to regular monthly pay, and a bonus month does not push an employee into a higher slab.
Is AP professional tax the same as Telangana professional tax?
Both states trace their law to the 1987 Act, which Telangana adapted after bifurcation in 2014, so the structure is similar. They are now separate laws with separate departments, portals and notifications. A business with staff in both Hyderabad and Visakhapatnam registers and pays in each State for the staff there.
Can I claim AP professional tax as an income tax deduction?
Salaried employees can deduct professional tax paid from salary income under the old tax regime, under Section 19 of the Income-tax Act, 2025 (Section 16(iii) of the 1961 Act up to FY 2025-26). The new tax regime does not allow it. Businesses generally claim it as an expense.
How much does professional tax registration assistance cost in Andhra Pradesh?
ProTax professional charges for professional tax registration assistance in Andhra Pradesh start at ₹1,499, covering registration or enrolment on the My Profession Tax portal and set-up of Form V filing. The profession tax itself, along with any interest or penalty, is paid separately at actuals to the Commercial Taxes Department.
Frequently Asked Questions
What is the professional tax slab in Andhra Pradesh for 2026?
For salary and wage earners, AP professional tax is nil up to ₹15,000 a month, ₹150 a month for ₹15,001 to ₹20,000, and ₹200 a month above ₹20,000, under entry 1 of the First Schedule to the Andhra Pradesh Tax on Professions, Trades, Callings and Employments Act, 1987. The same slab applies to men and women.
What is the maximum professional tax for an employee in Andhra Pradesh?
A salaried employee earning above ₹20,000 a month pays ₹200 a month, or ₹2,400 a year. Unlike Maharashtra, Andhra Pradesh has no higher February deduction. The ₹2,500 a year figure applies to enrolled persons such as companies, directors and professionals, which is the ceiling under Article 276 of the Constitution.
Who collects professional tax in Andhra Pradesh in 2026?
The Commercial Taxes Department collects profession tax from 1 April 2025, under G.O. Ms. No. 63 dated 5 March 2025. The department had collected it from 1987 to July 2012, after which municipal corporations handled it. Taxpayers now register, file and pay only on the department's portal.
How do I pay AP professional tax online?
Go to the Commercial Taxes Department website, apct.gov.in, open the My Profession Tax portal and use the taxpayer login. From there you can register, file the Form V return and pay online. Employers quote their registration number, and enrolled persons pay the annual amount shown in their enrolment certificate.
What is the due date for AP professional tax for employers?
Under Rule 12(1) of the AP profession tax Rules, as amended in 2011, an employer files the return in Form V along with the tax by the 10th day of the month after the month for which the return is due. So tax deducted from salaries paid in October is due by 10 November.
When must enrolled persons pay AP professional tax?
Under Section 10 of the Act, an enrolled person pays the year's tax before 30 June if enrolled before the year began or on or before 31 May. A person enrolled after 31 May pays within one month of the date of enrolment. The amount is stated in the enrolment certificate.
What is the difference between registration and enrolment in AP professional tax?
A registration certificate under Section 6(1) is held by an employer that deducts tax from employees' salaries and files Form V returns. An enrolment certificate under Section 6(2) is held by a company, director, professional, dealer or other person liable to pay the tax on their own account, usually once a year.
How much professional tax does a company pay in Andhra Pradesh?
A company registered under the Companies Act with turnover of ₹10 lakh or more pays ₹2,500 a year under entry 20. A company that is a GST-registered dealer falls under entry 8, with ₹1,250 for turnover of ₹10 lakh to ₹50 lakh and ₹2,500 above ₹50 lakh. The highest applicable entry governs.
Do directors pay professional tax in Andhra Pradesh?
Directors of companies, other than those nominated by the Government, are covered by entry 5 of the First Schedule at ₹2,500 a year. They take an enrolment certificate and pay the tax themselves. Where a director also draws salary, the annual cap of ₹2,500 per person still applies.
Do doctors and lawyers pay professional tax in Andhra Pradesh?
Professionals under entry 2, including legal practitioners, medical practitioners, engineers, architects and consultants, pay nil if their standing in the profession is up to five years, and ₹2,500 a year if it is more than five years. They enrol and pay by 30 June each year.
How much professional tax do shops and dealers pay in AP?
Under entry 8, GST-registered dealers and shopkeepers who employ staff under the AP Shops and Establishments Act pay nil below ₹10 lakh annual turnover, ₹1,250 a year for ₹10 lakh to ₹50 lakh, and ₹2,500 a year above ₹50 lakh. Restaurants, takeaways and curry points are under entry 39A at ₹2,500.
What is the penalty for late AP professional tax registration?
Under Section 6(5) of the Act, the assessing authority can impose a penalty of ₹10 to ₹20 per day of delay on an employer and up to ₹5 per day on others, after a hearing. Apply within 30 days of becoming liable. Deliberately false information in the application attracts a penalty of ₹100 to ₹1,000.
What is the interest on late payment of AP professional tax?
Section 11 makes an employer who fails to deduct or pay the tax an assessee in default, liable to interest for each month or part of the delay. Form V computes simple interest at 2% a month or part. The same applies to enrolled persons who pay late under Section 11(2).
What is the penalty for not paying AP professional tax after a demand?
If an assessee fails, without reasonable cause, to pay within the time in the notice of demand, Section 12 allows a penalty of 25% to 50% of the tax due, in addition to interest. Arrears of tax, penalty and interest are recoverable as arrears of land revenue under Section 13.
Is there a penalty for late Form V returns?
Under Section 7(3), if a registered employer fails without reasonable cause to submit the return within the specified period, the assessing authority can impose a penalty of ₹5 to ₹100 for each day of delay, after giving an opportunity to make a representation. A return without proof of tax payment is not treated as filed.
Who is exempt from professional tax in Andhra Pradesh?
Entry 39 of the First Schedule exempts agriculturists, persons performing religious duties, listed skilled workers such as goldsmiths, tailors, carpenters, plumbers and electricians, persons with 40% or more disability and dry cleaners. Salaried persons up to ₹15,000 a month pay nil. Section 31 lets the State notify further exemptions.
Is bonus included in salary for AP professional tax?
Section 2(m) of the Act defines salary or wages to include pay, dearness allowance, all other regular remuneration and perquisites under Section 17 of the Income-tax Act, 1961, but not bonus or gratuity. So the slab is applied to regular monthly pay, and a bonus month does not push an employee into a higher slab.
Is AP professional tax the same as Telangana professional tax?
Both states trace their law to the 1987 Act, which Telangana adapted after bifurcation in 2014, so the structure is similar. They are now separate laws with separate departments, portals and notifications. A business with staff in both Hyderabad and Visakhapatnam registers and pays in each State for the staff there.
Can I claim AP professional tax as an income tax deduction?
Salaried employees can deduct professional tax paid from salary income under the old tax regime, under Section 19 of the Income-tax Act, 2025 (Section 16(iii) of the 1961 Act up to FY 2025-26). The new tax regime does not allow it. Businesses generally claim it as an expense.
How much does professional tax registration assistance cost in Andhra Pradesh?
ProTax professional charges for professional tax registration assistance in Andhra Pradesh start at ₹1,499, covering registration or enrolment on the My Profession Tax portal and set-up of Form V filing. The profession tax itself, along with any interest or penalty, is paid separately at actuals to the Commercial Taxes Department.














